Understand your choices before moving retirement money

Make your 401(k) rollover decision with clarity

Leaving a job creates an important decision about your workplace retirement account. The best choice depends on your plan features, costs, investment options, service needs, tax situation, and wider retirement strategy.

Schedule a conversation
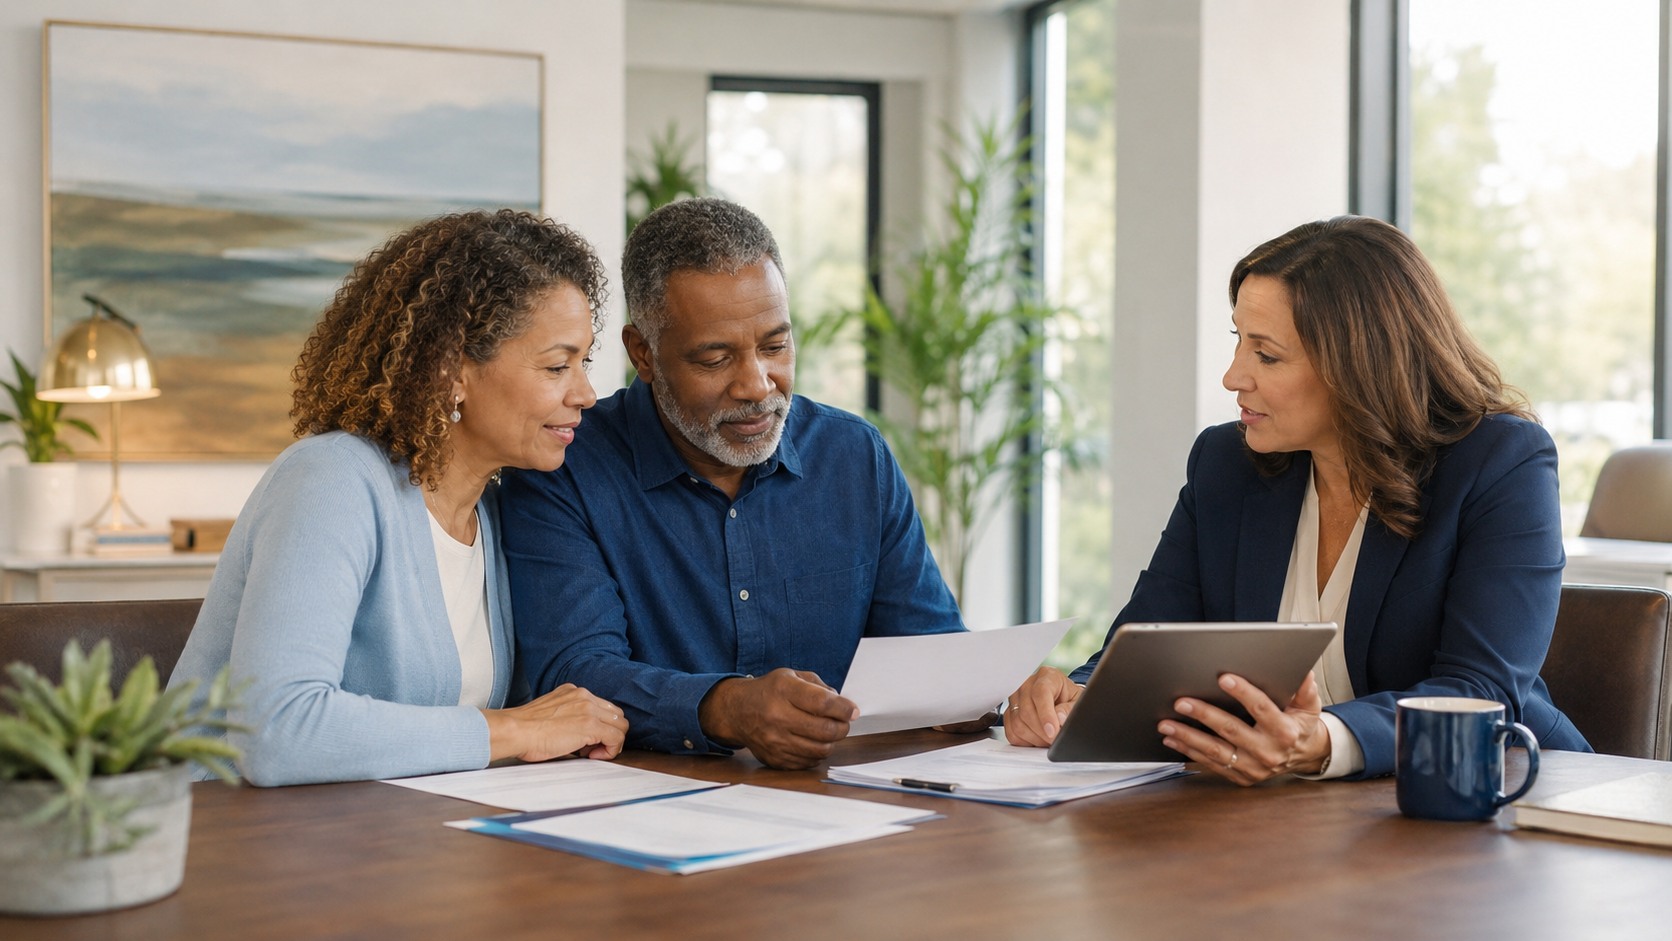
A couple reviewing retirement-account choices with a financial educator
01

Four common choices

Depending on plan rules and eligibility, you may be able to leave money in a former employer’s plan, move it to a new employer’s plan, roll it to an IRA, or take a taxable distribution. Each choice has different features and consequences.

02

Direct and indirect rollovers

A direct rollover generally sends eligible funds directly to the receiving plan or IRA and can avoid mandatory withholding. With an indirect rollover, the distribution is paid to you; eligible amounts generally must be redeposited within the applicable deadline, and withholding may create an out-of-pocket shortfall.

03

Compare more than investment choices

Review administrative and investment expenses, available funds, advice and service, withdrawal flexibility, creditor protections, required minimum distribution rules, loan treatment, beneficiary options, and access to institutional pricing before deciding.

04

Taxes and early-distribution rules matter

A properly completed rollover can preserve tax deferral. Taking cash may create current taxable income and, depending on age and circumstances, an additional federal tax. Employer stock, after-tax contributions, Roth balances, and outstanding plan loans may require special analysis.

05

Coordinate the rollover with retirement income

A rollover should support—not replace—your full plan for emergency reserves, near-term spending, Social Security, pensions, investment risk, insurance protection, healthcare, and future income needs.

Important information

Synergy Wealth and Health Strategies LLC does not provide tax or legal advice. Rollovers may affect fees, investment options, services, withdrawal rights, creditor protection, and taxes. Consult the current plan administrator and qualified tax or legal professionals before completing a transaction. No rollover strategy eliminates all fees, charges, or market risk.
Your next step

Review your rollover options before acting

Bring your latest statement and plan information to an educational comparison of the choices available to you.

Start the conversation