Plan for care while protecting dignity and choices

Long-term care planning is family protection

Extended help with everyday activities can affect savings, retirement income, housing, and the people providing care. Planning early can create more choices for where and how care is received.

Schedule a conversation
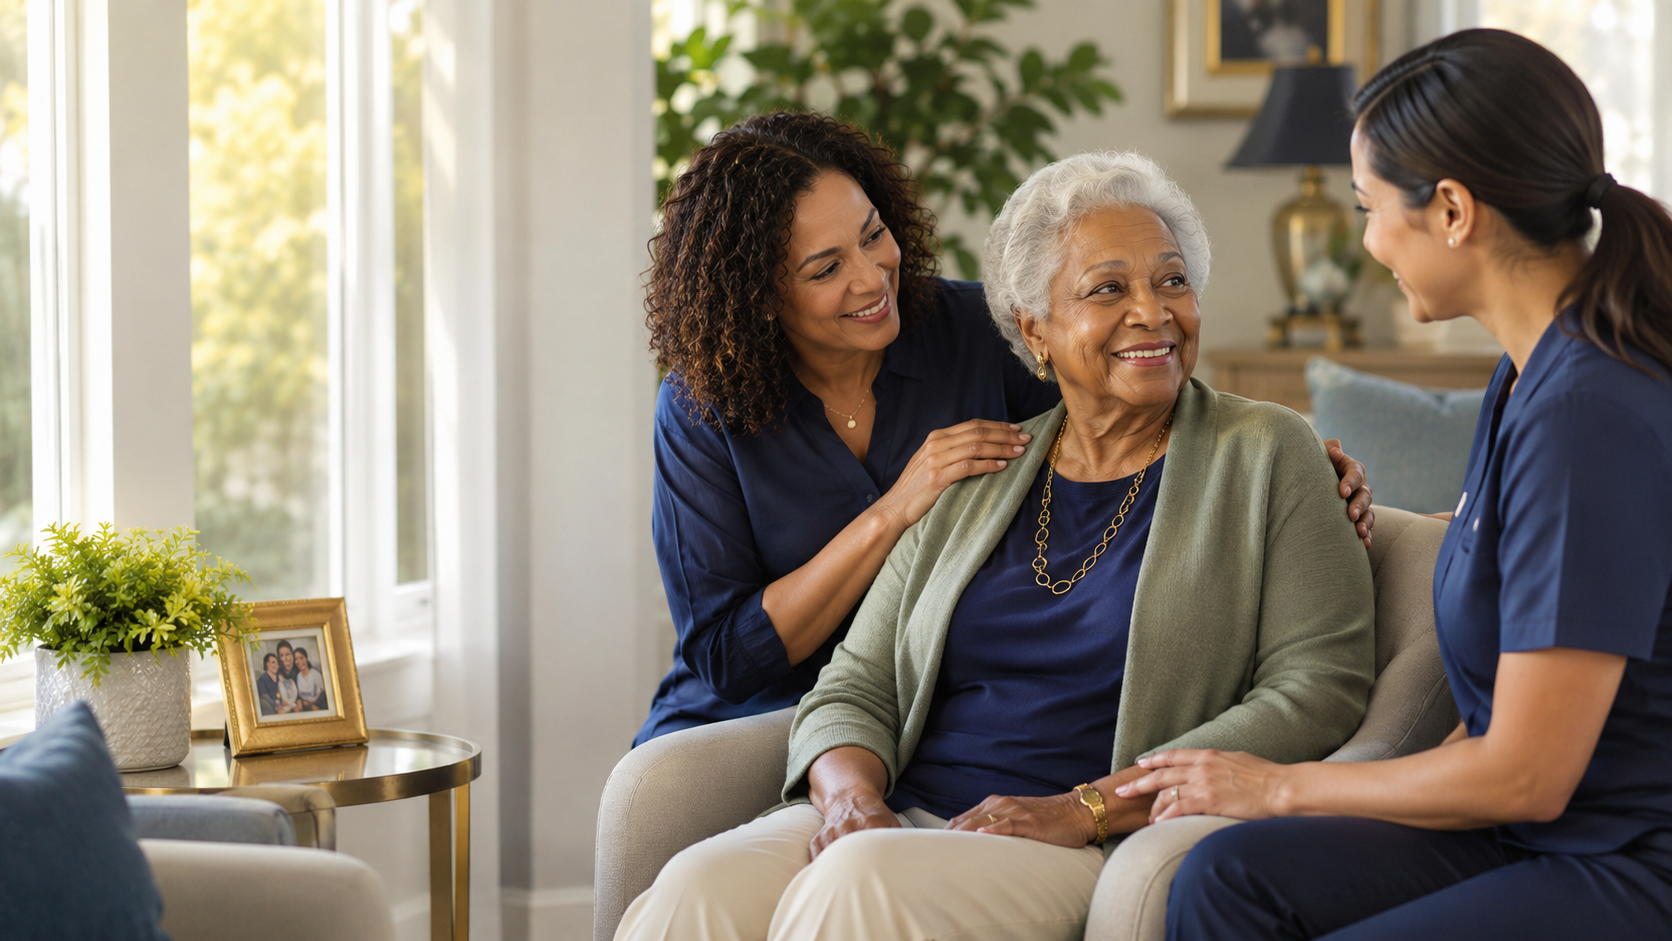
An older adult receiving supportive care at home from family and a professional caregiver
01

What long-term care includes

Long-term care may include help with activities such as bathing, dressing, eating, transferring, toileting, and continence, as well as supervision related to cognitive impairment. Care can be delivered at home, in adult day programs, assisted living, memory care, or nursing facilities.

02

Health insurance and Medicare have limits

Medical insurance generally focuses on treating illness or injury. Medicare may cover eligible short-term skilled care under specific conditions, but it generally does not pay for ongoing custodial care when that is the only care needed.

03

Ways families may fund care

Potential resources include personal income and assets, family support, traditional long-term-care insurance, life insurance or annuity contracts with qualifying care benefits, certain government programs, and combinations of these approaches.

04

Traditional and linked-benefit coverage

Traditional long-term-care insurance may reimburse eligible covered expenses up to contract limits. Linked-benefit policies combine life insurance or an annuity with long-term-care features. Premiums, benefits, inflation options, elimination periods, underwriting, and residual death benefits vary widely.

05

Plan for the caregiver as well as the recipient

Caregiving can affect employment, income, health, and family relationships. A plan should discuss who will coordinate care, legal decision-making documents, housing preferences, available support, and how costs may be shared.

06

Earlier planning can preserve options

Age, health, family history, budget, assets, and preferences influence available choices. Waiting until care is needed may limit insurance eligibility, making an early educational review valuable even if no product is purchased.

Important information

Long-term-care benefits are subject to underwriting, eligibility definitions, elimination periods, exclusions, limits, charges, and state availability. Medicare and Medicaid rules are complex and may change. Synergy Wealth and Health Strategies LLC does not provide legal, tax, or Medicaid-planning advice.
Your next step

Start the care conversation before a crisis

We can help you identify potential care needs, family concerns, available resources, and insurance questions to discuss.

Start the conversation